
Central Clearing Ccp Waterfall
SEC Rule 17Ad-22(e)(18) U.S. Treasury Cash & Repo Central Clearing Mandate: Scope, Deadlines & FICC Impact
Following March 2020 "Dash-for-Cash" and September 2019 repo market dislocations, SEC Rule 17Ad-22(e)(18) brings trillions in bilateral inter-dealer cash Treasuries and hedge-fund/money-fund Treasury repos into central clearing at DTCC FICC.
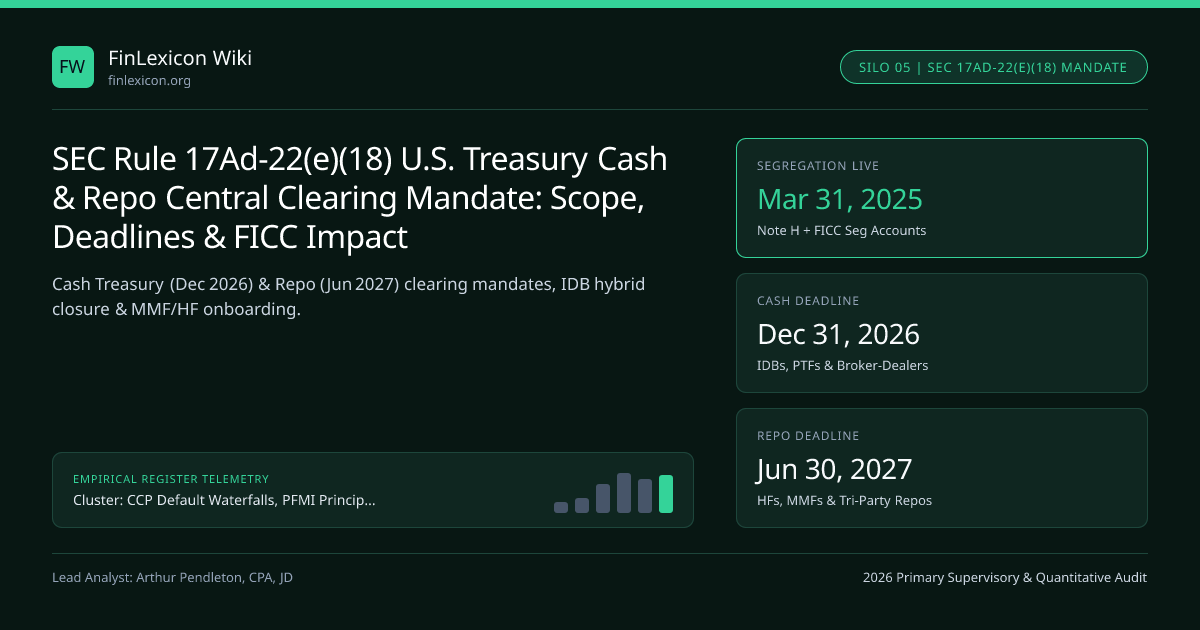
Prior to the U.S. SEC’s historic December 13, 2023 Final Rule (Release No. 34-99149, amending 17 CFR § 240.17Ad-22(e)(18)), over 80% of U.S. Treasury repo volume and nearly 70% of cash U.S. Treasury volume traded UNCLEARED (or "hybrid-cleared" on electronic PTF inter-dealer platforms with zero CCP margin!)! Guided by the Inter-Agency Working Group on Treasury Market Surveillance (IAWG — U.S. Treasury, Federal Reserve, NY Fed, SEC, CFTC), SEC Rule 17Ad-22(e)(18) represents the largest structural transformation of the $28+ trillion U.S. Treasury market in 40 years.
How SEC Rule 17Ad-22(e)(18) Enforces Clearing Indirectly Through Direct FICC Participants#
Spot the clever jurisdictional architecture of SEC Rule 17Ad-22(e)(18) anchored in our CCP Default Waterfalls & Central Clearing cornerstone guide: unlike Dodd-Frank Title VII (which gave CFTC direct statutory power over every swap counterparty), the SEC regulates Covered Clearing Agencies (CCAs — currently DTCC’s Fixed Income Clearing Corporation [FICC] Government Securities Division [GSD], alongside incoming CME / ICE Treasury CCP entrants)!
- Therefore, Rule 17Ad-22(e)(18)(iv)(A) requires FICC’s own rulebook to mandate that every Direct FICC Netting Member (
all Primary Dealers likeBank of America, BNP Paribas Securities Corp, and BMO Capital Markets) submit 100% of its "Eligible Secondary Market Transactions" (ESMTs) for central clearing—sweeping hedge funds, money-market funds (MMFs), and principal trading firms (PTFs) in whenever they face an FICC Direct Member!
Exact Scope: What Is In (Cash vs Repo) vs Statutory Exemptions (Central Banks, Corporates, Affiliates)#
SEC Rule 17Ad-22(e)(18) splits Eligible Secondary Market Transactions (ESMTs) into two starkly different scopes (Cash is narrower; Repo is almost universal!):
- U.S. Treasury Repo & Reverse Repo (
Broad Sweep!):
- Covers ALL repurchase and reverse repurchase agreements collateralized by U.S. Treasury securities in which at least one counterparty is a Direct FICC Participant—sweeping in bilateral uncleared
$0-haircuthedge-fund basis-trade repos, tri-party BNY Mellon MMF repos, and inter-dealer GCF/DVP repos!
- Outright Cash U.S. Treasury Purchases & Sales (
Targeted Inter-Dealer / Broker / IDB Sweep):
- Covers secondary-market cash Treasury trades involving a Direct FICC Participant ONLY where the counterparty is: (a) brought together by an Inter-Dealer Broker (
IDB, curing "hybrid clearing" where PTFs traded anonymously against FICC dealers!), OR (b) a registered Broker-Dealer, Government Securities Broker, or Government Securities Dealer! (Note: after public comment, the SEC dropped* outright cash Treasury buys/sells by hedge funds and asset managers from the cash mandate!)*
- Statutory Exclusions:
- Central Banks, Sovereign Governments, International Financial Institutions (
e.g.,ADB / IMF / World Bank), and State/Local Governments (exempt on both Cash and Repo!). - Inter-Affiliate Repo Exemptions (
conditional on clearing external-facing legs!). - Non-Financial Corporate Treasury Repos (
under narrow cash-management conditions / SEC FAQs).
| Counterparty Facing FICC Direct Dealer | Outright Cash U.S. Treasury Trade | U.S. Treasury Repo / Reverse Repo | Primary Clearing Access Model |
|---|---|---|---|
Inter-Dealer Broker (IDB) / Electronic PTF | MANDATORY CLEARING (Dec 31, 2026) | MANDATORY CLEARING (Jun 30, 2027) | Direct Netting / Agent Clearing |
| Registered Broker-Dealer / Gov. Sec. Dealer | MANDATORY CLEARING (Dec 31, 2026) | MANDATORY CLEARING (Jun 30, 2027) | Direct / Correspondent / Agent |
| Hedge Fund / Asset Manager / Pension | EXEMPT (Dropped from Final Cash Rule!) | MANDATORY CLEARING (Jun 30, 2027) | Sponsored Repo or Agent Clearing (ACM) |
2a-7 Money-Market Fund (MMF) | EXEMPT (Cash) | MANDATORY CLEARING (Jun 30, 2027) | Sponsored General Collateral (SGC Tri-Party) |
Central Bank / Sovereign / Multilateral (ADB) | EXEMPT | EXEMPT | Exempt Sovereign Carve-Out |
Phased Implementation Timeline (Including SEC’s February 2025 1-Year Compliance Extension!)#
To prevent operational bottlenecks while onboarding thousands of buy-side funds and legal documentation (SIFMA Cleared Repo Annex), the SEC issued a 1-year extension in February 2025 (Release No. 34-102487) establishing this three-stage rollout:
- Stage 1 — March 31, 2025 (Completed on Schedule!): FICC rulebook overhauls effective for segregated customer margin accounts, SEC Rule 15c3-3a Note H customer margin on-posting, and done-away access frameworks.
- Stage 2 — December 31, 2026 (
Extended from Dec 31, 2025): Mandatory central clearing of all eligible Cash U.S. Treasury transactions! - Stage 3 — June 30, 2027 (
Extended from June 30, 2026): Mandatory central clearing of all eligible U.S. Treasury Repo & Reverse Repo transactions!
Ending $0-Haircut Bilateral Hedge-Fund Treasury Basis-Trade Leverage#
Why did the Federal Reserve and Financial Stability Oversight Council (FSOC) champion mandatory repo clearing? In bilateral uncleared repo, dealers lent cash to relative-value hedge funds at 0% haircut (netting repo vs reverse-repo risks internally); under central clearing, FICC charges risk-based VaR Initial Margin on every directional net portfolio, curbing hidden 50x–100x Treasury cash-futures basis leverage (partially offset via CME-FICC cross-margining) across the CCP Default Waterfalls & Central Clearing topic hub!
Unlocking Dealer Balance-Sheet Capacity (ASC 210-20 Netting) & Multi-CCP Competition#
Routing bilateral repo into FICC unlocks $400B–$1T+ of dealer GAAP/SLR balance-sheet netting via FICC Sponsored Repo while spurring CME Securities Clearing and ICE Clear Credit to launch competing SEC-registered Treasury CCPs!
- [ I( RepoUST ) + I( CashUST ) * I( Counterparty in { IDB , BrokerDealer , GovSecDealer } ) ]
- Hedge-Fund Basis-Trade Margin Impact ($10.0B Long Cash UST Repo + -$10.0B Short CME UST Futures):
- Uncleared Bilateral Repo (Legacy): $0.0M Repo Haircut + $165.0M CME Futures IM = $165.0M Total IM (~60x Leverage)
- Standalone Cleared FICC Repo : +$210.0M FICC VaR IM + $165.0M CME Futures IM = $375.0M Total IM (Unless Cross-Margined!)
Frequently asked questions
What was "Hybrid Clearing" on Treasury Inter-Dealer Broker (IDB) screens, and why did the NY Fed view it as a systemic blind spot?
On electronic IDB platforms (BrokerTec, Fenics), high-frequency Principal Trading Firms (PTFs, non-FICC members) matched anonymously against Primary Dealers (FICC members): the IDB cleared the Primary Dealer leg at FICC while settling the PTF leg bilaterally with zero CCP margin—leaving IDBs exposed to unmargined intraday PTF default risk during March 2020!
Why did the SEC exempt Hedge Funds and Mutual Funds from Cash Treasury clearing while forcing them into Repo clearing?
Outright cash Treasury purchases settle overnight (T+1 Delivery-versus-Payment DvP), carrying minimal 24-hour replacement risk for unlevered cash buyers; by contrast, Treasury Repo funds massive multi-week leveraged carry and cash-futures basis positions (exceeding $1 trillion), creating acute systemic fire-sale risk!
Can a 1940-Act Money Market Fund (MMF) post Default Fund or CCLF commitments to FICC when its repos clear?
NO — SEC Rule 2a-7 / Investment Company Act Section 17(f) prohibits MMFs from mutualizing CCP default losses! Therefore, MMFs clear via FICC Sponsored General Collateral (SGC) or Agent Clearing (ACM), where the Sponsoring Bank (e.g., BofA, BNY, JPMorgan) satisfies all FICC Clearing Fund and CCLF obligations on the MMF’s behalf!
Will DTCC FICC remain the sole monopoly U.S. Treasury clearing house after 2026–2027?
No! SEC Rule 17Ad-22(e)(18) triggered historic market entry: both CME Group (CME Securities Clearing) and Intercontinental Exchange (ICE Clear Credit Treasury Service) filed SEC Covered Clearing Agency applications to compete head-to-head with DTCC FICC for cash and repo Treasury clearing!
Publication record
- Published
- 13 November 2026
- Updated
- 16 November 2026
- Author
- Arthur Pendleton, CPA, JD
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Arthur Pendleton, CPA, JD. (2026, November 16). SEC Rule 17Ad-22(e)(18) U.S. Treasury Cash & Repo Central Clearing Mandate: Scope, Deadlines & FICC Impact. FinLexicon Wiki. https://finlexicon.org/wiki/sec-rule-17ad-22-e-18-us-treasury-cash-repo-central-clearingRelated Central Clearing Ccp Waterfall & Institutional Briefings
Explore Central Clearing Ccp Waterfall Hub (20) →Central Clearing Ccp Waterfall
CCP Default Waterfalls, CPMI-IOSCO PFMI, VMGH, LSOC Segregation & Treasury Central Clearing GuideCentral Clearing Ccp Waterfall
FICC Sponsored Member Repo: Done-With vs Done-Away Execution, ASC 210-20 Netting & SLR ReliefCentral Clearing Ccp Waterfall
SEC Exchange Act Rule 15c3-3a Note H: Broker-Dealer Customer U.S. Treasury Margin On-Posting to FICCCentral Clearing Ccp Waterfall
FICC Capped Contingency Liquidity Facility (CCLF): Cover-1 Repo Liquidity Sizing & Bank LCR ImpactCentral Clearing Ccp Waterfall
CCP Margin Anti-Procyclicality (APC): EMIR RTS Article 28 25% Buffer, 10-Year Stress Weight & Margin FloorsCentral Clearing Ccp Waterfall
CCP Default Management Groups (DMG), Macro Hedging, Auction Juniorization & 2018 Nasdaq LessonsCentral Clearing Ccp Waterfall
Basel III CRE54 Qualifying CCP (QCCP) Capital: 2% vs 4% Client Trade Exposure Risk Weights & K_CCPCentral Clearing Ccp Waterfall
CCP Intraday Variation & Ad-Hoc Margin Calls: Dash-for-Cash Liquidity Spirals & One-Way Pass-ThroughRegulatory Compliance
Financial Services Regulatory ESG updater - Global Regulation TomorrowRegulatory Compliance
SEC enforcement actions fall 24%, crypto cases in spotlightRegulatory Compliance
Economies are improving, but rule of law is slipping. The buck now stops with Africa’s leaders | Kenneth MohammedPayment Systems
Europe payment market shifts as ECB allows non-bank financial institutions direct settlement -
FinLexicon Wiki Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.