
Central Clearing Ccp Waterfall
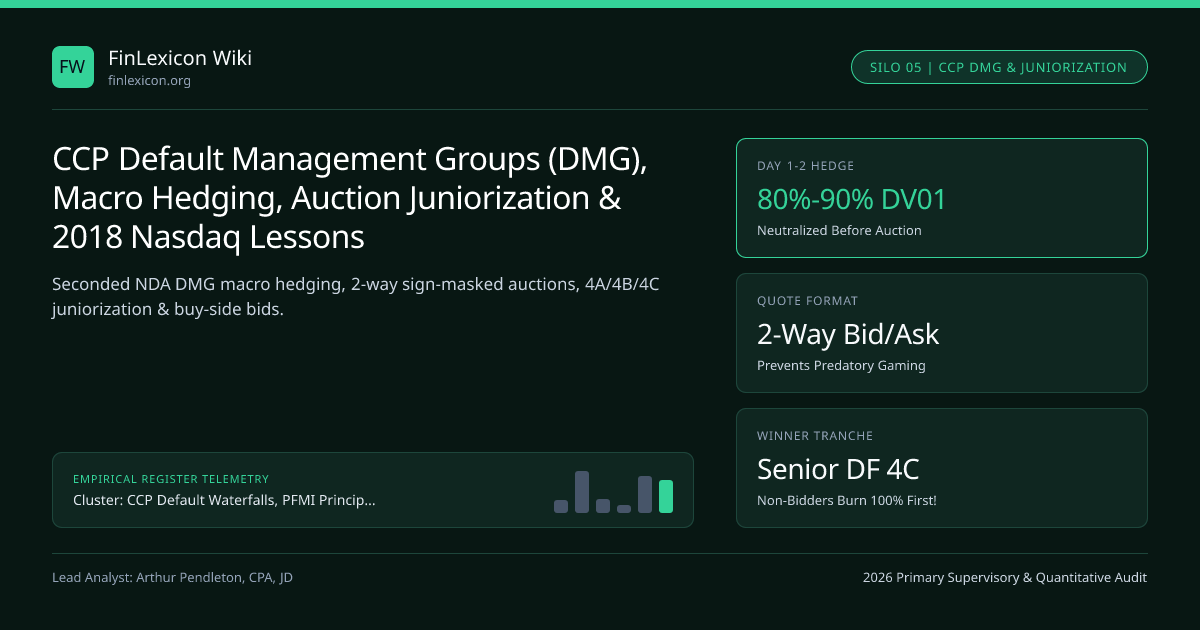
CCP Default Management Groups (DMG), Macro Hedging, Auction Juniorization & 2018 Nasdaq Lessons
When a G-SIB clearing member defaults at 7:00 AM with 250,000 open swap tickets, dumping raw line items would spark fire sales; step inside the CCP Default Management Group (DMG) war room to see macro hedging, 2-way auctions, and DF juniorization.
When Lehman Brothers Special Financing Inc. defaulted at LCH SwapClear on September 15, 2008 leaving $9 trillion notional across 66,390 interest-rate swaps in 5 currencies, LCH didn’t call brokers in a panic: within hours, senior rates traders seconded from surviving dealers (like Bank of America and BNP Paribas) walked through security into LCH’s information-barrier Default Management Group (DMG) war room, executed macro delta hedges reducing directional DV01 by 85%+ inside 72 hours, and auctioned all 5 currency books with 65% of Lehman’s Initial Margin left untouched!
Inside the DMG War Room: Seconded Dealer Traders, Information Barriers & Porting Split#
Codified across LCH Default Rules, CME IRS / ICE Clear Credit DMG charters, and Eurex DMC protocols overseen by the Bank of England, CFTC / Federal Reserve, and ECB, a systemic derivatives CCP executes a crisp 5-day (House) / 7-day (Client) close-out sequence, anchored in our CCP Default Waterfalls & Central Clearing cornerstone guide:
- Hour 0–2 (
Default Notice & Client Porting Separation): Upon failure to meet morning Variation Margin, the CCP issues a formal Default Notice, freezes House proprietary positions, and immediately separates LSOC / EMIR ISA-OSA Client accounts into a24–48 hourporting track toward backup FCMs. - Hour 2–6 (
DMG Convening & Chinese-Wall Quarantine): Pre-designated senior traders from rotating Clearing Member banks (e.g., 6–10 dealers per asset class) sign strict statutory Non-Disclosure Agreements (NDAs)—legally barred from communicating position signs or concentrations back to their employer’s trading desk! - Day 1–3 (
Macro Risk Neutralization — Hedging 80%–90% of Delta/Vega FIRST!): Never auction an unhedged directional whale! Using liquid benchmark swaps (2Y, 5Y, 10Y, 30Y SOFR / Bund futures) executed anonymously across multiple dealers, the DMG neutralizes80%–90%of first-order curve DV01 and gamma so the portfolio stops bleeding MTM while auction packs are assembled!
Preventing "Predatory Front-Running" & the 2018 Nasdaq Clearing Concentration Failure#
Why did LCH’s 2008 Lehman auction cost 0% of the Default Fund, whereas Nasdaq Clearing’s September 2018 Einar Aas power default burned EUR 107M (68% of surviving members’ Default Fund)?
- Market Size & Concentration Trap: Einar Aas held a Nordic-vs-German power spread larger than multiple days of entire market volume, and only 4 surviving utility bidders were invited into the emergency auction (
every bidder instantly knew the exact directional sign of Aas’s whale book and demanded massive risk discounts!). - Modern Anti-Predation Auction Engineering:
- Sub-Portfolio Decomposition (
splitting USD, EUR, GBP, JPY, Basis, and Inflation into separate digestible currency/product auction packs). - Symmetric / "Noise" Hedging & Sign Masking (
requiring dealers to submit two-way Bid AND Offer prices on the auction pack—if bidders must quote both to buy AND to sell the anonymized risk pack before learning which way the CCP trades, predatory one-sided lowballing backfires!).
Game-Theory Genius: Mandatory Bidding & Three-Tier Default Fund "Auction Juniorization"#
What stops surviving G-SIBs (Bank of America, BNP Paribas, Bank of Montreal) from submitting a lazy -$500M lowball bid in the CCP auction? Default Fund Juniorization ("Bidders’ Incentive Tranching") inside the CCP Default Waterfall!
Suppose the winning auction price pierces Defaulter IM + CCP SITG, requiring $600M from Surviving Members’ $5.0B Mutualized Default Fund. Instead of hitting all survivors equally, the CCP re-orders (juniorizes) the Default Fund into three priority sub-tranches:
- Sub-Tranche 4A (
100% Burned FIRST!) — Non-Bidders & Invalid/Extreme-Outlier Bidders (dealers obligated to bid in that currency who failed to bid or bid outside the band). - Sub-Tranche 4B (
Burned SECOND) — Non-Winning / Wide Bidders (dealers who bid worse than the auction clearing price). - Sub-Tranche 4C (
Senior-Most / Protected LAST!) — Winning Bidders (the dealers who actually stepped up and won the auction pack!).
Game-Theory Result: Every dealer races to submit a razor-sharp competitive bid so its $250M Default Fund contribution jumps into protected Senior Sub-Tranche 4C!
| Survivor Default Fund Sub-Tranche | Auction Bidding Behavior of Member | Loss-Absorption Priority | Economic Game-Theory Effect |
|---|---|---|---|
Sub-Tranche 4A (Junior-Most) | Obligated dealer failed to bid or submitted sham bid | Wiped Out 100% FIRST! | Eliminates auction boycott / free-riding |
Sub-Tranche 4B (Mezzanine) | Submitted valid bid, wider than clearing price | Absorbs loss ONLY after 4A = $0 | Penalizes defensive/wide pricing |
Sub-Tranche 4C (Senior-Most) | Won the auction (or within tight threshold of winner) | Protected LAST (untouched unless 4A+4B wiped out!) | Incentivizes aggressive market-clearing bids! |
| Invited Buy-Side Bidder | Hedge fund / PTF bidding via Clearing Broker | No DF at risk (earns alpha on auction discount!) | Expands risk-bearing capital beyond G-SIBs |
Allowing Direct Buy-Side (Client) Participation in CCP Default Auctions#
Following CPMI-IOSCO’s 2020 Auction Guidance, LCH, CME, ICE, and Eurex expanded default-auction onboarding to allow pre-vetted hedge funds, asset managers, and PTFs (submitting bids Sponsored/Guaranteed through their Clearing Broker) to compete directly in DMG auctions—multiplying auction liquidity and prevents narrow 4-dealer bottlenecks across the CCP Default Waterfalls & Central Clearing topic hub!
Mandatory Annual CCP Default Fire Drills (CFTC, EMIR & BoE Rules)#
At least once or twice every year, systemic CCPs run full-scale multi-day simulated Default Fire Drills (with real test portfolios sent to every clearing bank’s trading desk), grading bid turnaround times and fining or suspending members who miss drill SLA cutoffs!
- Dealer Optimal Auction Bid Reservation Price B_optimal (Incorporating Default Fund Juniorization Saving!):
- ExpectedPayoff(Win @ Bid B) = ( FairValuePack - CostCapitalKVA - BidB ) + ExpectedDFLossSavedByMoving4Bto_4C!
- => Dealers rationally bid tighter than standalone KVA breakeven to shield their $100M–$300M Default Fund tranche!
Frequently asked questions
How can a bank’s trader sit inside the CCP’s DMG war room AND have that same bank bid in the auction without insider trading?
Strict physical and electronic Information Barriers (Chinese Walls) audited by regulators! The trader seconded to the CCP’s DMG works in a locked CCP facility (no personal phone, no Bloomberg chat to home bank) until the default closes, while a *completely separate* team back at the bank prices the anonymized auction pack sent to all bidders!
Why are Clearing Members legally REQUIRED to bid in CCP default auctions for asset classes they actively trade?
Under LCH SwapClear, CME IRS, and ICE Clear Credit rulebooks, any dealer clearing above a threshold notional in a currency/asset class has a mandatory contractual bidding obligation (backed by Sub-Tranche 4A 100% Default Fund juniorization!), ensuring deep liquidity even during systemic panic!
What happens to Client positions if they fail to port to a backup FCM within the 24–48 hour porting window?
If a client lacks a pre-signed backup FCM (or no backup FCM accepts the client’s credit/KYC in time), the CCP closes out (hedges and auctions) that client’s positions alongside or separately from the house book, deducts close-out costs from the client’s IM, and returns any surplus (directly via EMIR Art. 48(7) leapfrog for ISA clients!).
Why does macro hedging on Day 1–2 matter so much if the whole portfolio will be auctioned on Day 4 anyway?
Because 66,000 bespoke off-market swaps take 3 to 4 days to clean, validate, and price by 20 auction bidders—without Day-1 liquid benchmark macro hedges (5Y/10Y swaps & futures), 4 days of unhedged market drift during a Lehman-scale crash could double close-out losses!
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Arthur Pendleton, CPA, JD
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Arthur Pendleton, CPA, JD. (2026, November 14). CCP Default Management Groups (DMG), Macro Hedging, Auction Juniorization & 2018 Nasdaq Lessons. FinLexicon Wiki. https://finlexicon.org/wiki/ccp-dmg-default-management-hedging-neutralization-auctionsRelated Central Clearing Ccp Waterfall & Institutional Briefings
Explore Central Clearing Ccp Waterfall Hub (20) →Central Clearing Ccp Waterfall
CCP Default Waterfalls, CPMI-IOSCO PFMI, VMGH, LSOC Segregation & Treasury Central Clearing GuideCentral Clearing Ccp Waterfall
Basel III CRE54 Qualifying CCP (QCCP) Capital: 2% vs 4% Client Trade Exposure Risk Weights & K_CCPCentral Clearing Ccp Waterfall
CCP Intraday Variation & Ad-Hoc Margin Calls: Dash-for-Cash Liquidity Spirals & One-Way Pass-ThroughCentral Clearing Ccp Waterfall
Cross-Margining Across Futures & Cleared Fixed Income: CME-FICC Treasury Offsets & Dual BD/FCMsCentral Clearing Ccp Waterfall
CLS Payment-versus-Payment (PvP) FX Settlement: Eliminating Herstatt Risk & 99% Pay-In NettingCentral Clearing Ccp Waterfall
CCP Assessment Powers & Cooling-Off Periods: Capped Cash Calls vs Uncapped Refills & Bank CapitalCentral Clearing Ccp Waterfall
EU CCP Recovery & Resolution Regulation (CCPRRR 2021/23) vs US Dodd-Frank Title II/VIII: NCWO & Bail-InCentral Clearing Ccp Waterfall
CCP Initial Margin Models (Expected Shortfall vs SPAN 2): 5-Day House vs 7-Day Client MPOR & PortingMonetary Policy
Bowman, The U.S. Economy and Considerations for Monetary PolicyRegulatory Compliance
New regulation for heating oil market, but no price controlsMarket Insights
Oil down more than $7 a barrel in post settlement trade as Trump signals restraint on IranMarket Insights
Why the US midterms sparked an AI stock selloff
FinLexicon Wiki Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.