
Central Clearing Ccp Waterfall
CCP Skin-in-the-Game (SITG): EMIR 25% Minimum Capital Rule, Second-Tranche SITG & Incentive Alignment
For-profit publicly listed exchanges own today’s systemic clearing houses—creating moral hazard if CCP shareholders suffer tiny losses while clearing banks fund multi-billion-dollar Default Funds; examine EMIR’s 25% Skin-in-the-Game formula and EU CCPRRR’s Second-Tranche SITG.
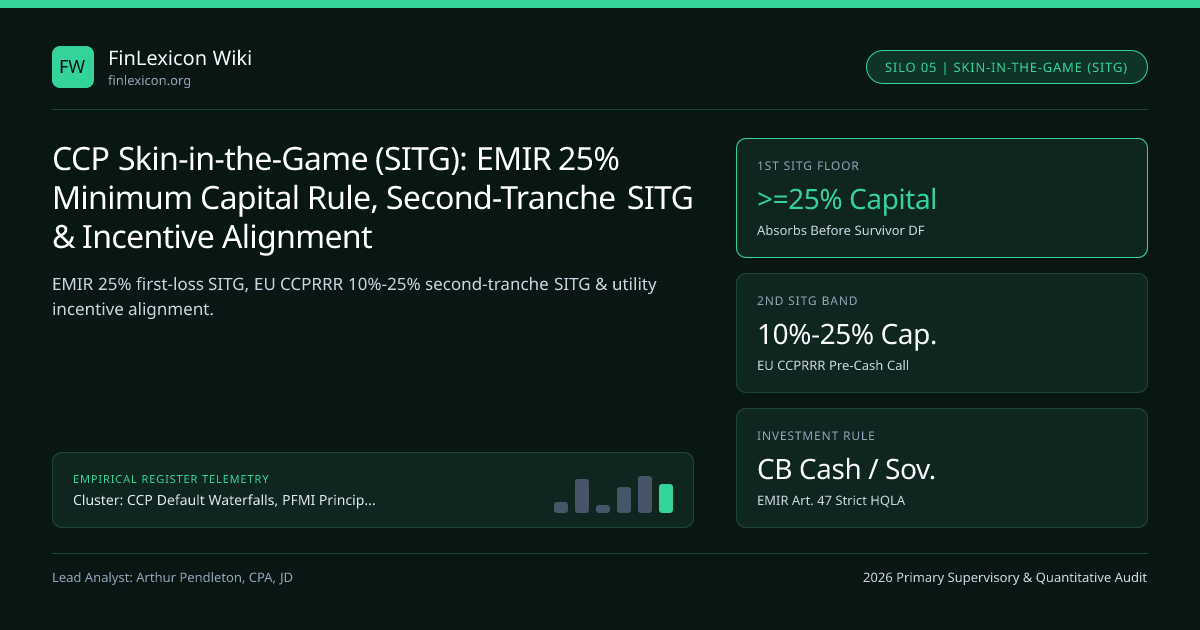
Thirty years ago, clearing houses were member-owned utilities; today, the world’s largest CCPs are owned by for-profit, publicly traded exchange groups (LSEG, CME Group, Deutsche Börse, Intercontinental Exchange). Look at the asymmetric governance tension pointed out repeatedly by Bank of America, BNP Paribas, and FIA/ISDA bank coalitions: the CCP operator sets Initial Margin models, approves new exotic products, and collects clearing fees—while Clearing Members supply 97%–99% of the mutualized Default Fund! CCP Skin-in-the-Game (SITG) is the statutory equity tranche designed to align those incentives.
How EU EMIR RTS 153/2013 Sizes First-Tranche Skin-in-the-Game (25% of Minimum Capital)#
Under EU EMIR Article 45(4) and Commission Delegated Regulation (EU) No 153/2013 (Article 35)—retained in UK CCP rules by the Bank of England and mirrored globally—every CCP must dedicate a slice of its own shareholder equity (SITG) inside the 6-tranche CCP Default Waterfall seated immediately ABOVE the defaulter’s own IM/DF and immediately BELOW surviving members’ Default Fund, anchored in our CCP Default Waterfalls & Central Clearing cornerstone guide.
How is EMIR Minimum Regulatory Capital (and thus the 25% SITG floor) calculated under EMIR RTS 152/2013?
- Winding-Down / Restructuring Expense: Minimum 6 months (
50%) of gross annual operational expenses. - Operational & Legal Risk Capital (
Basic Indicator or AMA). - Credit, Counterparty & Market Risk Capital on the CCP’s own treasury investment portfolio (
NOT cleared trades!). - Business Risk Capital (
minimum 25% of annual gross operational expenses).
- First-Tranche SITG Formula:
SITG_1 >= 25% * Capital_EMIR_Minimum, allocated across compartmentalized Default Funds proportional to each Default Fund’s size!
The G-SIB vs Exchange Debate: Why 25% of CCP Capital Often Equals Only 1%–3% of the Default Fund!#
Spot the arithmetic catch highlighted by ISDA, FIA, and 20 global clearing banks: because a CCP’s operational capital (e.g., $300M) scales with IT/staff overhead rather than $150 trillion of cleared derivatives risk, 25% of $300M equals $75 million of SITG—sitting directly in front of a $6,000 million ($6.0B) member-funded Default Fund (just 1.25% of the Default Fund!)!
- What Clearing Banks Argue: SITG should scale dynamically with risk (
e.g., 5%–10% of the Cover-2 Default Fund) so an exchange cannot rush an illiquid product to market with99%survivor-funded protection. - What CCP Operators & CPMI-IOSCO Counter: CCPs are risk-neutral market-infrastructure utilities (
collecting 0.1–0.5 bps clearing fees, NOT 15% ROE risk-taking banks!); forcing a CCP to hold$1.5Bof first-loss equity (wiped out on 1 tail event) would either triple client clearing fees or decapitalize the CCP corporation mid-crisis when markets need the CCP operating!
The European Compromise: EU CCPRRR (2021/23) "Second-Tranche Skin-in-the-Game" (SSITG)#
When the European Union enacted the CCP Recovery and Resolution Regulation (`CCPRRR`, Regulation (EU) 2021/23, Article 9(14)) supervised by ESMA and national authorities alongside the ECB, lawmakers introduced a clever two-layer SITG compromise:
- First-Tranche SITG (
25%of risk-based capital) stays above the Pre-Funded Default Fund (protecting members from small tail breaches). - NEW Second-Tranche SITG (
SSITG— calibrated under ESMA RTS2023/840between10%and25%of risk-based capital!) sits AFTER the Pre-Funded Default Fund, right BEFORE or pari-passu with non-defaulting members’ Recovery Cash Calls / VMGH—ensuring CCP management cannot trigger member cash calls orVMGHrecovery tools pain-free!
U.S. CFTC & SEC Market Practice: Voluntary Corporate SITG Commitments ($100M–$250M+)#
Although neither the CFTC nor the SEC codified a hard 25% statutory formula like EMIR, competitive pressure from clearing banks led CME Clearing ($100M IRS + $100M Base + $50M futures corporate contributions), ICE Clear Credit ($50M), and DTCC FICC (25% corporate allocation of retained earnings) to hard-code explicit first-loss SITG tranches into their rulebooks across the CCP Default Waterfalls & Central Clearing topic hub.
| CCP / Regulatory Framework | First-Tranche SITG Rule (Pre-Survivor DF) | Second-Tranche SITG Rule (Pre-Recovery Calls) | Pro-Rata Silo Split Rule |
|---|---|---|---|
EU CCPs (Eurex, LCH SA — EMIR + CCPRRR) | >= 25% of EMIR Minimum Capital | 10%–25% of Risk-Based Capital (ESMA RTS 2023/840) | Allocated strictly proportional to each Default Fund |
UK CCPs (LCH Ltd, ICE Clear Europe) | >= 25% of UK EMIR Minimum Capital | BoE CCP Supervisory Recovery alignment | Ring-fenced per service (SwapClear, ForexClear, etc.) |
CME Clearing (U.S. CFTC SIDCO) | Rulebook Dedicated Corporate Contribution ($100M Base, $150M IRS) | Governance & cooling-off protections | Dedicated dollar commitment per clearing silo |
DTCC FICC / NSCC (U.S. SEC SIFMU) | >= 25% of retained net income Corporate Contribution (Rule 4) | Board replenishment discretion (Member-owned utility!) | Allocated across GSD, MBSD, and NSCC |
SITG Replenishment Rules & Restriction on Executive Bonuses / Dividends#
Whenever a default pierces First- or Second-Tranche SITG, CCP rulebooks require replenishing SITG within 20–30 business days (out of retained earnings/parent equity, never billed to clearing members!) and trigger automatic dividend and executive variable-bonus freezes under EU CCPRRR!
- SITGFirstSilod = ( 0.25 * CapEMIRMin ) * [ DFPreFundedd / Sum{m=1..D} DFPreFundedm ]
- SITGSecondCCPRRR = alphaESMA * ( CapOpRisk + CapTreasuryInvestRisk + CapBizRisk ) where alphaESMA in [ 0.10 , 0.25 ]
Frequently asked questions
Why would setting SITG at 100% of a CCP’s equity actually be dangerous for financial stability?
If a Cover-2 default wiped out 100% of a CCP’s regulatory capital, the CCP itself would immediately breach its statutory 6-month winding-down capital license floor—forcing regulators to shut down or resolve the clearing house right in the middle of a financial crisis! Keeping ~55%–65% of core operational capital un-pledged keeps the CCP operating seamlessly.
How does ESMA RTS 2023/840 decide whether an EU CCP’s Second-Tranche SITG is 10% or 25%?
Commission Delegated Regulation (EU) 2023/840 scores four objective indicators (each worth up to 3.75% above the 10% base): (1) structure/cross-default complexity, (2) absence of member governance committee vetoes, (3) non-cash/risky treasury investment profile, and (4) frequency of margin backtesting breaches (pushing riskier CCPs toward the full 25% cap)!
Does higher CCP Skin-in-the-Game lower a bank’s Basel CRE54 Default Fund Capital Charge?
Yes, directly! In Basel CRE54, the QCCP’s dedicated SITG (DF_CCP) is subtracted from K_CCP (or increases total pre-funded resources DF_pref), directly lowering surviving banks’ regulatory capital requirement on their Default Fund contributions!
Can a CCP invest its Skin-in-the-Game equity in corporate equities or high-yield bonds to boost ROE?
Strictly NO! Under EMIR RTS 153/2013 Articles 45 & 47, a CCP’s regulatory capital (including SITG) must be invested exclusively in central-bank cash or ultra-liquid, minimal-credit-risk sovereign bonds (HQLA) capable of immediate same-day liquidation during a default!
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Arthur Pendleton, CPA, JD
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Arthur Pendleton, CPA, JD. (2026, November 14). CCP Skin-in-the-Game (SITG): EMIR 25% Minimum Capital Rule, Second-Tranche SITG & Incentive Alignment. FinLexicon Wiki. https://finlexicon.org/wiki/skin-in-the-game-sitg-emir-25-percent-capital-incentive-alignmentRelated Central Clearing Ccp Waterfall & Institutional Briefings
Explore Central Clearing Ccp Waterfall Hub (20) →Central Clearing Ccp Waterfall
CCP Default Waterfalls, CPMI-IOSCO PFMI, VMGH, LSOC Segregation & Treasury Central Clearing GuideCentral Clearing Ccp Waterfall
Variation Margin Gains Haircutting (VMGH), Partial Tear-Up & End-of-Waterfall CCP Recovery ToolsCentral Clearing Ccp Waterfall
Client Clearing Segregation: US CFTC Part 22 LSOC vs EU EMIR Article 39 Omnibus (OSA) & Individual (ISA)Central Clearing Ccp Waterfall
SEC Rule 17Ad-22(e)(18) U.S. Treasury Cash & Repo Central Clearing Mandate: Scope, Deadlines & FICC ImpactCentral Clearing Ccp Waterfall
FICC Sponsored Member Repo: Done-With vs Done-Away Execution, ASC 210-20 Netting & SLR ReliefCentral Clearing Ccp Waterfall
SEC Exchange Act Rule 15c3-3a Note H: Broker-Dealer Customer U.S. Treasury Margin On-Posting to FICCCentral Clearing Ccp Waterfall
FICC Capped Contingency Liquidity Facility (CCLF): Cover-1 Repo Liquidity Sizing & Bank LCR ImpactCentral Clearing Ccp Waterfall
CCP Margin Anti-Procyclicality (APC): EMIR RTS Article 28 25% Buffer, 10-Year Stress Weight & Margin FloorsRegulatory Compliance
Water industry bonus ban to be tightened as Ofwat warns of ‘damage to public trust’Market Insights
Nomura's head of crypto derivatives trading swaps Dubai for a prop trading firm in Singapore - eFinancialCareersRegulatory Compliance
Europe Launches Industry Group to Set Tokenized Securities Settlement Rules - CCN.comRegulatory Compliance
Financial Services Regulatory ESG updater - Global Regulation Tomorrow
FinLexicon Wiki Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.