
Central Clearing Ccp Waterfall
EU CCP Recovery & Resolution Regulation (CCPRRR 2021/23) vs US Dodd-Frank Title II/VIII: NCWO & Bail-In
What if a systemic clearing house fails NOT from a member default, but from a $2B cyberattack, custodian bank failure, or treasury investment loss ("Non-Default Loss — NDL")? Compare EU CCPRRR (2021/23), UK BoE FMI Resolution, and U.S. Dodd-Frank Title II/VIII!
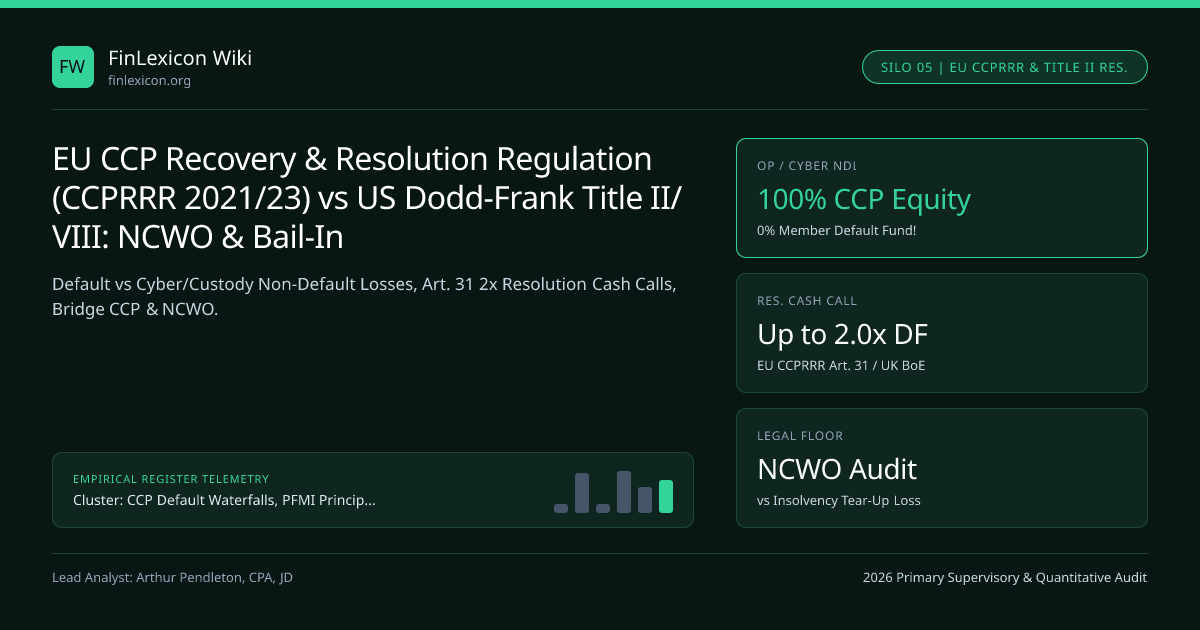
Every clearing waterfall article focuses on Default Losses (DL — when a Clearing Member blows up)—yet what if the CCP ITSELF suffers a $1.5 billion "Non-Default Loss" (NDL) because a commercial custodian bank holding CCP cash fails, the CCP’s own repo investment book implodes, or a nation-state cyberattack/fraud drains operational reserves?! Who pays for NDLs—CCP shareholders (LSEG, CME, Deutsche Börse) or Clearing Member banks (like BNP Paribas and Bank of America)? And when does the state step in? Welcome to EU CCPRRR (Regulation 2021/23), UK FSMA 2023 CCP Resolution, and U.S. Dodd-Frank Title II / VIII!
Default Losses (DL) vs Non-Default Losses (NDL): Drawing the Shareholder Responsibility Line#
Highlighted in *FSB’s April 2024 Final Report (Financial Resources and Tools for CCP Resolution)* and CPMI-IOSCO NDL Guidance, regulators led by the BIS / FSB, Bank of England, ECB, and Federal Reserve split Non-Default Losses into two distinct buckets, anchored in our CCP Default Waterfalls & Central Clearing cornerstone guide:
- Operational, Cyber, Fraud & Legal
NDLs(100%CCP Shareholder Responsibility!):
- Clearing Members have zero control over the CCP’s IT firewalls or internal fraud controls—therefore operational/cyber
NDLsMUST be absorbed100%by CCP equity, parent guarantees, insurance, and statutory Equity Write-Down / Bail-In (0%billed to Clearing Members’ Default Fund!).
- Custody & Treasury Investment
NDLs(Often Shared Above a CCP Deductible!):
- Wait: what if
EUR 5Bof cash collateral had to be invested in commercial bank repos (or held at a custodian) and that counterparty defaulted? Many CCP rulebooks (and EU CCPRRR Art. 9 / CFTC rules) make the CCP absorb a dedicated first-loss NDL tranche (e.g., $100M–$200M), while allocating catastrophic residual investment/custody losses pro-rata across clearing participants (unless the CCP held100%of cash risk-free at the Central Bank under Dodd-Frank 806(a) / ECB deposit accounts!)!
Inside EU CCPRRR (Regulation (EU) 2021/23, Fully Live Since Feb 2023) & UK FSMA 2023#
Regulation (EU) 2021/23 (CCPRRR) (mirrored closely by the UK’s enhanced **Bank of England CCP Special Resolution Regime** under FSMA 2023) creates a dedicated three-stage crisis continuum (Recovery -> Early Intervention -> Public Resolution) when private recovery threatens financial stability:
- Resolution Entry Conditions (
Art. 22): (1) CCP is failing or likely to fail (FOLTF), (2) no private recovery measure prevents failure without systemic contagion, AND (3) public interest requires continuity of critical clearing services (avoiding standard corporate insolvency!). - Four Statutory Resolution Authority Powers (
Art. 27–44):
- Position & Loss Allocation Tools: Statutory VMGH and Partial / Full Tear-Up.
- Statutory "Resolution Cash Call" (
Art. 31): Exclusive to the Resolution Authority! Can demand up to2.0x(200%) of surviving Clearing Members’ pre-funded Default Fund on top of private capped recovery assessments! - Write-Down and Conversion (
Bail-Inof CCP Equity & Debt,Art. 32–35): Wipes out CCP shareholders (essential for Non-Default Losses!) and converts CCP parent debt into equity. - Sale of Business / Bridge CCP Tool (
Art. 40–42): Transfers healthy clearing silos (e.g., SwapClear / Bund futures) overnight into a clean state-controlled Bridge CCP!
The Tricky NCWO ("No Creditor Worse Off") Counterfactual Valuation (CCPRRR Art. 60)#
Borrowed from bank BRRD / TLAC resolution, Article 60 of EU CCPRRR (and UK FSMA 2023) guarantees No Creditor Worse Off (NCWO): no clearing member, client, or shareholder may suffer a larger loss in Resolution than they would have suffered if the Resolution Authority had NOT stepped in and instead let the CCP execute full rulebook tear-up and wind down under normal insolvency law!
- Watch the NCWO Paradox: If a CCP’s private rulebook already includes
100%VMGH+Full Tear-Up + Limited Recourse, then in the insolvency counterfactual ITM gainers already took huge losses—UNLESS the Resolution Authority steps in EARLY (skipping contractual tear-up and imposing a 2x Resolution Cash Call on Out-of-the-Money banks to spare ITM pension funds!), in which case those OTM banks gain anNCWOcompensation claim (funded by recouping CCP cash flows or public backstops)!
Transatlantic Contrast: U.S. Dodd-Frank Title VIII + Title II (FDIC Orderly Liquidation Authority)#
In the United States (CME, ICE, DTCC FICC, OCC), there is no standalone "CCPRRR" statute; instead, if a Title VIII SIFMU exhausted its CFTC/SEC recovery plan (Dodd-Frank Sec. 805 / 17 CFR 39.39), the Treasury Secretary (with two-thirds votes of the Federal Reserve and FDIC Boards under **Dodd-Frank Title II**!) can appoint the FDIC as Receiver, transfer critical clearing contracts to a Bridge Financial Company, and draw temporary Orderly Liquidation Fund (OLF) liquidity from the U.S. Treasury (repaid 100% via industry assessments, zero taxpayer bailout) across the CCP Default Waterfalls & Central Clearing topic hub!
| CCP Resolution Dimension | EU CCPRRR (Reg. 2021/23) | UK FSMA 2023 (Sched. 11 BoE Regime) | U.S. Dodd-Frank Title VIII & Title II |
|---|---|---|---|
| Lead Resolution Authority | National Resolution Authority + ESMA College | Bank of England (FMI Resolution Directorate) | FDIC (appointed via Fed + FDIC + Treasury 3-keys) |
| Statutory Resolution Cash Call | Up to 2.0x Pre-Funded DF (Art. 31) | Up to 2.0x DF (Default) / 3x OpEx (NDL` CCP) | Governed by rulebook + Title II OLF industry recoup |
Initial Margin Haircutting (IMH) | Strictly Prohibited | Permitted ONLY in extreme last resort / practically nil (BoE policy prioritizes VMGH) | Protected customer property (CEA 4d / SIPA) |
| Temporary Public Liquidity Backstop | National / Eurosystem arrangements (strict conditions) | HM Treasury / BoE resolution liquidity (recouped) | Title II Orderly Liquidation Fund (OLF) |
Cross-Border Resolution Crisis Management Groups (CMGs)#
Because LCH SwapClear (London), CME (Chicago), and Eurex (Frankfurt) clear trades for banks in 40+ countries simultaneously, the FSB mandates CCP Crisis Management Groups (CMGs) uniting BoE, Fed, CFTC, SEC, ECB, ESMA, and JFSA so foreign authorities immediately recognize cross-border VMGH and Bridge-CCP transfers!
- Example Early-Intervention NCWO Trigger:
- Counterfactual (No Early Resolution): Private VMGH haircuts ITM Pension Fund -$400M; OTM Bank pays $0 extra Cash Call.
- Actual Resolution (Authority Skips Private VMGH & Fires Art. 31 1.5x Resolution Cash Call on OTM Bank = -$120M):
- => OTM Bank suffered -$120M > $0 Counterfactual Loss -> OTM Bank earns +$120M Statutory NCWO Claim (CCPRRR Art. 60–62)!
Frequently asked questions
Do CCPs have to issue billions in TLAC / MREL bail-in bonds like G-SIB banks?
No! In its April 2024 Final Report on CCP Resolution Resources, the Financial Stability Board (FSB) decided *against* imposing a bank-style Pillar 1 TLAC debt ratio on CCPs (because CCPs don’t hold risky loan books), requiring instead that Resolution Authorities verify sufficient toolbox resources for both Default and Non-Default Losses across CCP-specific CMGs!
Why is Custody / Investment Non-Default Loss treated differently from Cyber / Fraud Non-Default Loss?
If Clearing Members post $50B of USD cash to a European CCP (which has no Fedwire 806(a) account and MUST reverse-repo or custody that USD at commercial banks under strict EMIR Art. 47 rules!), CCPs argue they are acting as pass-through cash custodians rather than profit-seeking speculators—leading many rulebooks to share extreme investment defaults *above* a CCP first-loss deductible!
Can a Resolution Authority step in BEFORE 100% of the CCP’s private recovery tools (like Full Tear-Up) have been used?
YES (CCPRRR Art. 22(3))! Waiting for a CCP to execute Full Service Tear-Up (wiping out $150 trillion of global interest-rate hedges!) would *cause* the exact systemic meltdown resolution exists to prevent—so Resolution Authorities have explicit power to intervene early whenever remaining private recovery steps would destabilize financial markets (paying NCWO if order changes)!
Has any CCP ever been placed into statutory public Resolution under EU CCPRRR or Dodd-Frank Title II?
Zero to date (through 2026)! Modern CCP historical failures (Paris Caisse de Liquidation 1974, Kuala Lumpur Commodity KLCE 1983, Hong Kong Futures Guarantee Corp 1987 stock crash) all pre-dated modern PFMI Cover-2, STM, and DMG architectures—and inspired today’s multi-layered waterfalls!
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Arthur Pendleton, CPA, JD
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Arthur Pendleton, CPA, JD. (2026, November 14). EU CCP Recovery & Resolution Regulation (CCPRRR 2021/23) vs US Dodd-Frank Title II/VIII: NCWO & Bail-In. FinLexicon Wiki. https://finlexicon.org/wiki/eu-ccprrr-ccp-recovery-resolution-regulation-cash-calls-ncwoRelated Central Clearing Ccp Waterfall & Institutional Briefings
Explore Central Clearing Ccp Waterfall Hub (20) →Central Clearing Ccp Waterfall
CCP Default Waterfalls, CPMI-IOSCO PFMI, VMGH, LSOC Segregation & Treasury Central Clearing GuideCentral Clearing Ccp Waterfall
CCP Initial Margin Models (Expected Shortfall vs SPAN 2): 5-Day House vs 7-Day Client MPOR & PortingCentral Clearing Ccp Waterfall
Clearing Novation vs Open-Offer Mechanics, Multilateral Netting & TriOptima Portfolio CompressionCentral Clearing Ccp Waterfall
CPMI-IOSCO PFMI Principles 4 & 7: Cover-2 Credit Default Fund vs Cover-1 / Cover-2 Liquidity SizingCentral Clearing Ccp Waterfall
CCP Default Waterfall Tranches: Defaulter-Pay IM/DF, Skin-in-the-Game & Survivor MutualizationCentral Clearing Ccp Waterfall
CCP Skin-in-the-Game (SITG): EMIR 25% Minimum Capital Rule, Second-Tranche SITG & Incentive AlignmentCentral Clearing Ccp Waterfall
Variation Margin Gains Haircutting (VMGH), Partial Tear-Up & End-of-Waterfall CCP Recovery ToolsCentral Clearing Ccp Waterfall
Client Clearing Segregation: US CFTC Part 22 LSOC vs EU EMIR Article 39 Omnibus (OSA) & Individual (ISA)Market Insights
Anthropic's IPO is major clearing event for AI trade: Melius' Ben ReitzesRegulatory Benchmarks
Prudential Banking, Clearing & Basel Capital Institutions 2026 Licensing Benchmark: 6D Prudential Scorecard Across 301 Audited EntitiesCompliance Forensics
How to Verify Prudential Banking, Clearing & Basel Capital Institutions Licences & Detect Clone Firms: 2026 Supervisory Lookup PlaybookSolvency and Protection
Investor Compensation Ceilings, Client-Money Segregation & Counterparty Risk Matrix in Prudential Banking, Clearing & Basel Capital Institutions (2026)
FinLexicon Wiki Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.