
Liquidity Coverage Nsfr Prudential
HQLA Level 1, 2A & 2B Haircuts: 40%/15% Composition Caps & Secured Funding Unwind (LCR30)
Under Basel LCR30, High-Quality Liquid Assets apply 0% Level 1, 15% Level 2A, and 25%–50% Level 2B haircuts while enforcing 40% and 15% composition caps both before and after 30-day repo unwinds.
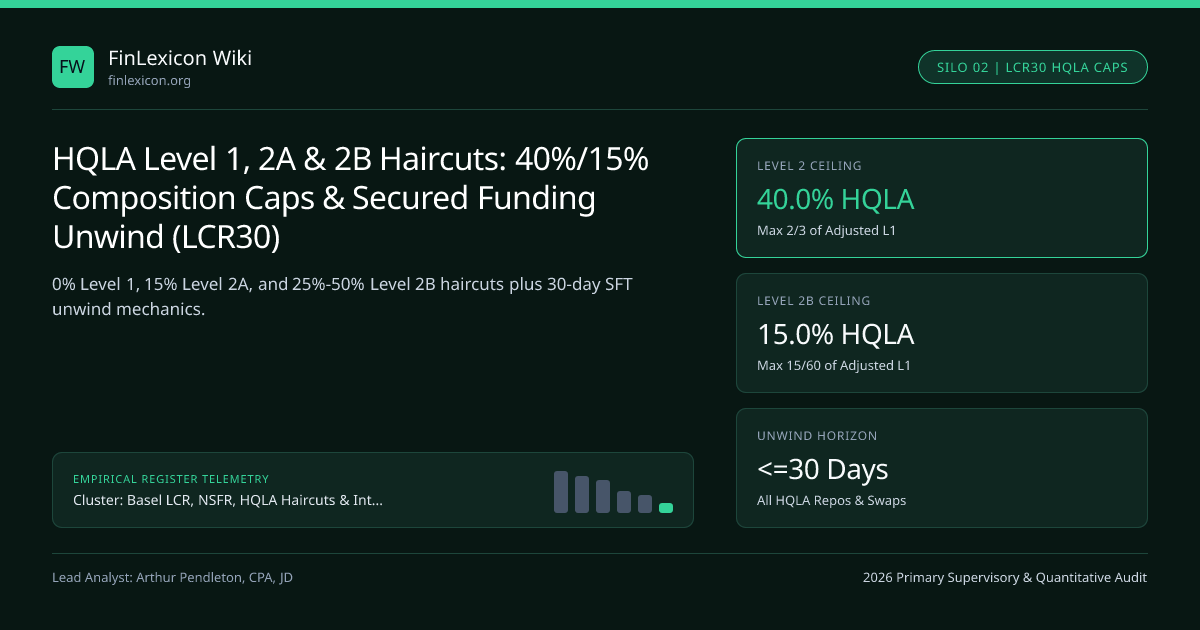
High-Quality Liquid Assets (HQLA) form the sole numerator of the Liquidity Coverage Ratio (LCR) & Level 1 HQLA Standard under Basel Framework chapter LCR30. To prevent banks from stuffing liquidity buffers with lower-tier corporate bonds or using sub-30-day reverse repos to evade composition caps, LCR30 stratifies eligible securities across Level 1 (0% haircut), Level 2A (15%), and Level 2B (25%–50%), enforcing 40% total Level 2 and 15% Level 2B caps on the stricter of pre-unwind and post-30-day-repo-unwind balances.
Operational Control by Treasury and Zero-Encumbrance Prerequisites (LCR30.13–31)#
Even a U.S. Treasury bill or Bund fails HQLA qualification if trapped inside an operating subsidiary subject to capital-transfer blocks or pledged as margin without instant substitution rights. As detailed in our Basel LCR, NSFR & HQLA cornerstone guide, LCR30.16–LCR30.27 mandates that HQLA remain legally and operationally unencumbered, free from accounting Held-to-Maturity lock-ups where monetization breaches tainting rules (unless clean repo monetization channels exist), and placed under the direct operational control of the treasury liquidity management function (demonstrated via periodic repo or outright test sales!).
Asset Eligibility & Haircuts: Level 1 (0%), Level 2A (15%), and Level 2B (25% / 50%)#
Tracked across the LCR-HQLA 2026 Benchmark Standard, LCR30 divides liquid securities into three tiers based on historical maximum 30-day repo haircut widening and price drop during the 2008 panic:
- Level 1 (
0% Haircut, Unlimited Share): Coin and banknotes, unrestricted central bank reserve balances (excluding required reserves unless drawable in stress), and marketable securities issued or guaranteed by sovereigns, central banks, BIS, IMF, ECB, or multilateral development banks like Asian Development Bank carrying a 0% Basel II/III credit risk weight (plus non-0% domestic-currency sovereign debt up to domestic net cash outflows). - Level 2A (
15% Haircut, Max 40% of Total HQLA): 20%-risk-weighted sovereign/PSE/agency securities (crucially including U.S. Fannie Mae and Freddie Mac Agency MBS under U.S. Reg WW!), plus AA- or higher non-financial corporate bonds and statutory covered bonds proven to have dropped<= 10%in price over 30 days in historical stress. - Level 2B (
25% RMBS / 50% Corporate & Equity Haircut, Max 15% of Total HQLA): High-grade AA+ residential MBS (25%haircut, excluded in U.S. Reg WW!), A+ to BBB- investment-grade non-financial corporate debt (50%haircut), and unencumbered main-index non-financial common equities (50%haircut). Zero securities issued by banks, insurers, broker-dealers, or financial affiliates ever qualify as Level 2A or 2B corporate/equity HQLA (except statutory covered bonds) to block financial cross-contagion!
Why LCR30.32 Unwinds All <=30-Day Secured Repos Before Testing the 40% & 15% Caps#
Suppose a dealer bank like Bank of America or BNP Paribas holds $40B Cash (Level 1) and $60B Agency MBS (Level 2A after 15% haircut = $51B). Without adjustment, Level 2A ($51B) exceeds 40/60 = 66.67% of Level 1 ($40B * 2/3 = $26.67B), causing $24.33B of Level 2A to be disqualified! Could the desk game the cap on Day 0 by repoing out $35B of Agency MBS for 7 days to raise $35B Cash (Level 1 = $75B, Level 2A = $21.25B -> zero cap breach!)?
No! LCR30.32–LCR30.38 mandates unwinding every secured funding, secured lending, and collateral swap transaction maturing within 30 calendar days involving HQLA on at least one leg, restoring the Day-30 post-unwind cash and bond balances (floored at zero adjusted Level 1), and taking the larger cap deduction between pre-unwind and post-unwind states!
| HQLA Tier & Asset Class | Basel LCR30 Haircut | Max Share of Total HQLA | U.S. Reg WW Treatment | Financial-Issuer Exclusion |
|---|---|---|---|---|
| Central Bank Reserves & 0%-RW Sovereigns | 0.0% (Level 1) | 100% (Unlimited) | Level 1 (incl. U.S. Treasuries & GNMA) | Central banks & sovereigns only |
| 20%-RW Sovereigns, PSEs & GSE Agency MBS | 15.0% (Level 2A) | 40% combined L2A + L2B | Level 2A (FNMA & FHLMC MBS) | GSEs explicitly eligible |
| AA- or Higher Corporate & Covered Bonds | 15.0% (Level 2A) | 40% combined L2A + L2B | AA- Corp L2A (Covered bonds excluded) | Bank/Financial corporate bonds BANNED |
| Qualifying AA+ Residential MBS | 25.0% (Level 2B) | 15% Level 2B ceiling | Excluded in U.S. Reg WW | Underlying mortgages non-affiliate |
| BBB- to A+ Corporate Debt & Index Equities | 50.0% (Level 2B) | 15% Level 2B ceiling | 50% L2B + IG Municipal Bonds | Financial-sector stocks & bonds BANNED |
U.S. Regulation WW Gold-Plating: GSE Agency MBS (Level 2A) & Municipal Caps#
Under 12 CFR Part 249, U.S. Treasuries and Ginnie Mae (GNMA) full-faith-and-credit MBS qualify as Level 1 (0% haircut), whereas Fannie Mae and Freddie Mac GSE MBS sit in Level 2A (15% haircut, 40% cap) while private-label RMBS and covered bonds are excluded entirely. Subsequent EGRRCPA statutory amendments admitted investment-grade U.S. general-obligation and revenue municipal bonds into Level 2B.
Monetization Without Market Impact: Diversifying Across Repo and Central Bank Lines#
Supervisors such as UK PRA, APRA (which eliminated the RBA Committed Liquidity Facility as Australian government bond supply grew), and HKMA require treasuries to avoid concentration in thin secondary issues across the Basel LCR, NSFR & Prudential Liquidity topic hub.
- AdjL2BExcess = max( 0 , AdjL2B - (15 / 85) * (AdjL1 + AdjL2A) , AdjL2B - (15 / 60) * Adj_L1 )
- AdjL2Excess = max( 0 , (AdjL2A + AdjL2B - AdjL2BExcess) - (2 / 3) * Adj_L1 )
- StockofHQLA = L1val + L2Aval + L2Bval - max( UnadjExcessTotal , AdjL2BExcess + AdjL2_Excess )
- Worked Audit ($60B L1 Reserves, $40B Gross L2A Agency MBS, $24B Gross L2B Russel-1000 Non-Fin Equities; Zero <=30d Repos):
- Haircutted Values: L1 = $60.0B | L2A = $40.0B * 0.85 = $34.0B | L2B = $24.0B * 0.50 = $12.0B
- Step 1 (L2B 15% Cap): min( (15/85)($60B+$34B) = $16.59B , (15/60)$60B = $15.00B ) => $12.0B <= $15.00B (Excess_L2B = $0)
- Step 2 (Total L2 40% Cap): Max Total L2 = (2/3) * $60.0B = $40.00B | Actual L2A + L2B = $34.0B + $12.0B = $46.00B
- Excess_L2 Deducted = $46.00B - $40.00B = $6.00B => Final Stock of HQLA = $60.0B + $34.0B + $12.0B - $6.0B = $100.00B!
Frequently asked questions
Why does a >30-day term repo of Level 2A Agency MBS genuinely expand HQLA when a 7-day repo does not?
A 35-day repo matures *outside* the 30-day LCR stress window: cash raised stays in Level 1 with 0% outflow in the next 30 days, and LCR30.32 only unwinds secured funding maturing *within* 30 calendar days, unlocking trapped excess Level 2A capacity.
Can mandatory minimum reserve balances at a central bank count as Level 1 HQLA?
Under LCR30.39, required reserves count in Level 1 HQLA ONLY to the extent the central bank’s operational framework explicitly permits those reserve balances to be drawn down during periods of idiosyncratic liquidity stress.
Why did Australia’s APRA phase out the Committed Liquidity Facility (CLF) in 2023?
Australia originally lacked sufficient Commonwealth and semi-government bond supply (AGS/Semis) for domestic banks like ANZ Bank to meet 100% HQLA without cornering the bond market; once public debt issuance expanded sufficiently post-2020, APRA retired the fee-based RBA CLF.
Do Held-to-Maturity (HTM) Treasury securities count in Level 1 HQLA at par or market value?
Always at fair market value! Even if an unencumbered U.S. Treasury sits in an amortized-cost HTM accounting portfolio at $100 par, LCR30 values it strictly at current clean/dirty market value (e.g., $86) provided treasury can monetize it via repo without tainting HTM.
Publication record
- Published
- 14 November 2026
- Updated
- 15 November 2026
- Author
- Arthur Pendleton, CPA, JD
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Arthur Pendleton, CPA, JD. (2026, November 14). HQLA Level 1, 2A & 2B Haircuts: 40%/15% Composition Caps & Secured Funding Unwind (LCR30). FinLexicon Wiki. https://finlexicon.org/wiki/hqla-level-1-2a-2b-haircuts-40-percent-adjusted-cap-unwindRelated Liquidity Coverage Nsfr Prudential & Institutional Briefings
Explore Liquidity Coverage Nsfr Prudential Hub (20) →Liquidity Coverage Nsfr Prudential
Basel III LCR, NSFR, HQLA Haircuts & Intraday Prudential Liquidity ArchitectureLiquidity Coverage Nsfr Prudential
LCR 30-Day Deposit Run-Off Rates (LCR40): Stable Retail (3%/5%), Operational (25%) & Financial (100%)Liquidity Coverage Nsfr Prudential
LCR 75% Aggregate Cash Inflow Cap: Performing Loan Rollovers, SFTs & the 25% HQLA FloorLiquidity Coverage Nsfr Prudential
LCR Derivatives Collateral Outflows: 24-Month Historical Look-Back Approach (HLBA) & Rating TriggersLiquidity Coverage Nsfr Prudential
Undrawn Credit vs Liquidity Facilities in LCR40: Corporate (10%/30%), Bank (40%) & SPV (100%)Liquidity Coverage Nsfr Prudential
NSFR Available Stable Funding (ASF) Factors (NSF30): Tier 1/2 Capital, Retail & Sub-1Y CliffsLiquidity Coverage Nsfr Prudential
NSFR Required Stable Funding (RSF) Weights (NSF30): Asset Encumbrance, 65% Mortgages & NPLsLiquidity Coverage Nsfr Prudential
Asymmetric NSFR Derivatives Treatment (NSF30): Cash VM Offsets & the 20% Gross Liability Add-OnIsda Csa Derivatives Collateral
1992 ISDA Market Quotation & Loss vs 2002 Close-Out Amount: Section 6(e) Early Termination ValuationIsda Csa Derivatives Collateral
ISDA Section 5(a) Events of Default vs Section 5(b) Termination Events: Cross-Default & Threshold AmountsIsda Csa Derivatives Collateral
2016 ISDA Variation Margin CSA: New York Security Interest Pledge vs English Law Title TransferIsda Csa Derivatives Collateral
Uncleared Margin Rules (UMR Phases 1–6): $8B/€8B AANA Calculation & the $50M/€50M IM Threshold
FinLexicon Wiki Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.