
Liquidity Coverage Nsfr Prudential
Collateral Swaps, Securities Lending & Liquidity Upgrade Trades: LCR30.36 Unwind & LCR40.48 Outflows
Borrowing Level 1 sovereign bonds against equities or corporate debt in a collateral swap boosts HQLA only when remaining maturity exceeds 30 days; sub-30-day upgrades vanish completely under the LCR30.36 unwind rule.
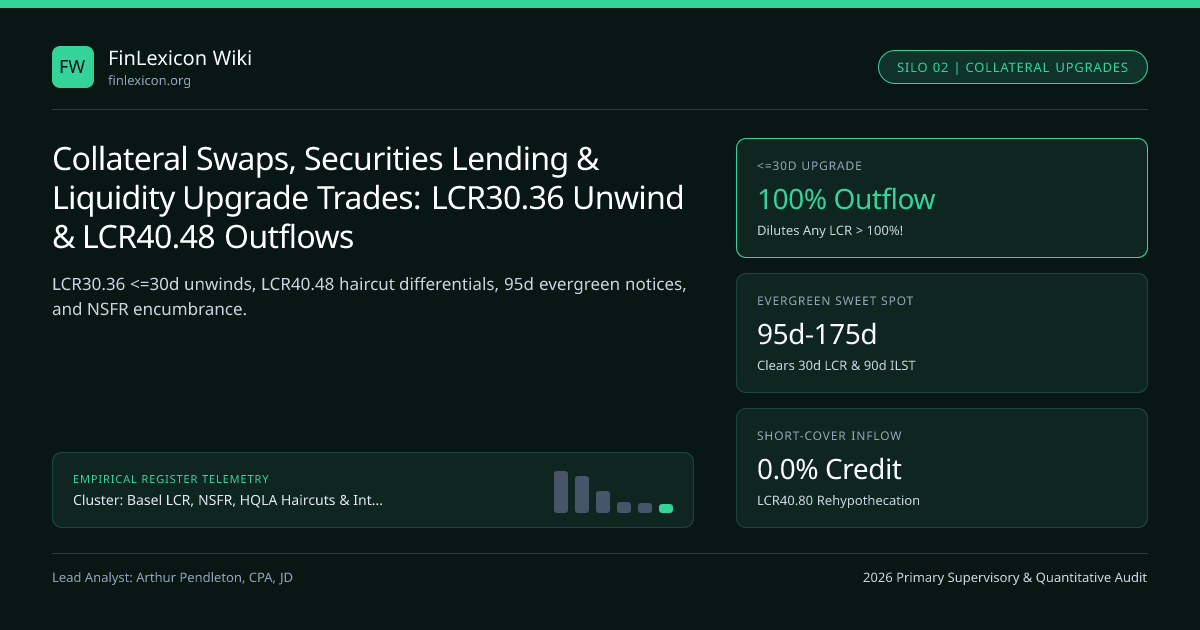
Before Basel III finalized its Securities Financing Transaction (SFT) rules, investment banks routinely executed "liquidity upgrade" collateral swaps—borrowing pristine Level 1 U.S. Treasuries or Gilts from pension funds and insurers against pledging illiquid equities, structured ABS, or non-HQLA corporate loans—to inflate headline liquidity buffers on reporting dates. Under Basel Framework paragraphs LCR30.36, LCR40.48, and LCR40.81, two interlocking rules neutralize short-term collateral swaps while pricing exact haircut differentials on sub-30-day rollovers.
Rule #1: Mandatory Unwind of < 30-Day Collateral Swaps Inside the HQLA Cap Engine (LCR30.36)#
Suppose a dealer borrows $10.0B of Level 1 U.S. Treasuries (0% haircut) in a 14-day collateral swap against posting $11.0B of Russell 2000 non-HQLA equities (100% non-HQLA). Does that $10.0B Treasury bond lift the bank’s LCR? Zero—actually, it leaves the bank strictly tied or worse off!
- LCR40.48 Net Outflow Charge (
Denominator): Because the collateral swap matures within<= 30 daysand the bank assumes non-rollover in stress, returning the$10.0BLevel 1 Treasury (0%haircut) while getting back$11.0Bof non-HQLA equities (100%haircut =$0HQLA value) generates a100% - 0% = 100%($10.0B) LCR Cash Outflow—consuming every penny of the$10.0BLevel 1 HQLA sitting in the numerator! - LCR30.36 Mandatory Cap Unwind (
Numerator): Even more decisively, when testing the 40% Level 2 and 15% Level 2B HQLA caps, LCR30.36 reverses the<= 30-daycollateral swap completely (Adjusted Level 1 = -$10.0B), preventing short-term borrowed Treasuries from unlocking extra Level 2A/2B bond capacity!

The Complete LCR40.48 Haircut-Differential Matrix for <= 30-Day Collateral Swaps#
Under LCR40.48 (and LCR40.81 for inflows on collateral downgrades), any collateral swap maturing within 30 calendar days generates a net LCR outflow (or inflow) equal to the difference between the LCR regulatory haircuts of the borrowed asset versus the lent asset, as linked to our Basel LCR, NSFR & HQLA cornerstone guide:
- Borrow Level 1 (
0%) vs Lend Level 2A (15%):15% - 0% =15% LCR Outflow. - Borrow Level 1 (
0%) vs Lend RMBS Level 2B (25%):25% - 0% =25% LCR Outflow. - Borrow Level 1 (
0%) vs Lend Corporate/Equity Level 2B (50%):50% - 0% =50% LCR Outflow. - Borrow Level 1 (
0%) vs Lend Non-HQLA (100%):100% - 0% =100% LCR Outflow! - Reverse Trade (Lend Level 1
0%vs Borrow Non-HQLA100%for<= 30d): Generates a 100% LCR Inflow (returning non-HQLA to reclaim your unencumbered Level 1 bond!), subject to the 75% aggregate inflow cap (LCR40.76) provided the borrowed non-HQLA was not rehypothecated to cover a short position!
Evergreen >30-Day Collateral Upgrades (e.g., 95-Day Rolling Notice) & Supervisory Guardrails#
To obtain genuine Pillar 1 LCR benefit from a collateral upgrade swap with an insurer or sovereign wealth fund, treasury desks structure trades with a minimum contractual maturity or evergreen notice period strictly > 30 calendar days (typically 95-day or 185-day evergreen notice):
- While remaining maturity exceeds
30 days,0%LCR outflow applies and noLCR30.36unwind occurs—adding full Level 1 HQLA! - Watch the Two Prudential Traps: First, the UK PRA, ECB, and Federal Reserve capture Day 31–95 collateral swap cliffs directly inside ILAAP / Reg YY 90-day survival stress tests. Second, if the collateral swap exceeds 6 months (
>= 180 days), NSFR encumbrance rules (`NSF30.20`) floor the pledged equity/loan’s RSF atmax(50%, 85%)(or 100% RSF if>= 1 year) while borrowing off-balance-sheet Treasuries adds 0% ASF!
| Asset Borrowed (Received) | Asset Lent (Pledged Out) | <= 30-Day LCR Outflow (LCR40.48) | <= 30-Day LCR Inflow (LCR40.81) | > 30-Day LCR HQLA Lift (per $100) |
|---|---|---|---|---|
Level 1 UST/Bund (0% cut) | Non-HQLA Equity/ABS (100% cut) | 100% Outflow ($100) | 0% Inflow | +$100 Level 1 HQLA (0% outflow) |
Level 1 UST/Bund (0% cut) | Level 2B Corporate/Equity (50% cut) | 50% Outflow ($50) | 0% Inflow | +$50 Net HQLA Upgrade ($100 - $50) |
Level 1 UST/Bund (0% cut) | Level 2A Agency/GSE (15% cut) | 15% Outflow ($15) | 0% Inflow | +$15 Net HQLA + Unlocks 40% Cap! |
Level 2A Agency (15% cut) | Non-HQLA Loan/Equity (100% cut) | 85% Outflow ($85) | 0% Inflow | +$85 Level 2A HQLA (if under 40% cap) |
Non-HQLA Equity (100% cut) | Level 1 UST/Bund (0% cut) | 0% Outflow | 100% Inflow (0% if short-covered!) | -$100 Level 1 HQLA (Downgrade lends HQLA) |
Short-Sale Covering Trap: Rehypothecated Client Collateral (100% Outflow / 0% Inflow)#
Prime brokerage desks at Bank of America, BNP Paribas, and Bank of Montreal must track rehypothecation lineage: if a bank borrows a security in a < 30d reverse repo or collateral swap and uses it to cover a customer or firm short position, LCR40.80 assigns 0% LCR Inflow (because unwinding the trade would force buying the security in the open market to cover the short!).
Pricing Collateral Upgrade Fees (25–55 bps) in LFTP Budgets#
Insurance companies lending Gilts, Bunds, or Treasuries for 3-to-12 months against IG corporate/equity baskets charge an agency upgrade fee (25–55 bps/year) benchmarked directly against bank unsecured term issuance spreads across the Basel LCR, NSFR & Prudential Liquidity topic hub.
- [ Standardized LCR40.48 form on notional X: Outflow = ( hLent - hBorrowed ) * X whenever hLent > hBorrowed ]
- LCRAfter30dUpgrade = ( HQLA0 + (1 - hBorrowed) * X ) / ( Outflow0 + (hLent - hBorrowed) * X )
- Mathematical Proof Why a <=30-Day Non-HQLA-for-Level-1 Swap LOWERS an Above-100% LCR ($80B HQLA0, $75B Out0 => 106.67%; $10B Swap: hBorrowed=0%, hLent=100%):
- New Numerator = $80.0B + $10.0B = $90.0B | New Denominator = $75.0B + (1.00 - 0.00) * $10.0B = $85.0B
- LCR_New = $90.0B / $85.0B = 105.88% < 106.67%! (Adding equal dollars to numerator & denominator shrinks any ratio > 100%!)
- With 95-Day Evergreen Notice (>30d): New Denominator stays $75.0B => LCR_New = $90.0B / $75.0B = 120.00% (+13.33% pts)
Frequently asked questions
Why does adding $10B of Level 1 HQLA and $10B of 30-day Outflow reduce a bank’s LCR from 120% to 117.6%?
By elementary fraction arithmetic, if HQLA / Outflows > 1.0 (e.g., $60B / $50B = 120%), adding identical +$10B to both numerator and denominator pulls the ratio downward toward 100% ($70B / $60B = 116.7%)! Thus <30d non-HQLA collateral upgrades dilute any passing LCR.
How does an "evergreen 95-day notice" collateral swap work operationally?
Unlike a fixed-date 95-day trade that decays below 90 days tomorrow and below 30 days on Day 66, an evergreen 95-day notice trade resets its 95-day residual maturity every business day unless and until either counterparty serves formal termination notice—starting a 95-day countdown clock!
Why did the UK PRA restrict insurance-to-bank liquidity upgrade swaps under supervisory guidelines?
Concerned about systemic interconnectivity—where an insurer lends Gilts it suddenly needs during a liability-driven investment (LDI) margin spiral at the exact moment the borrowing bank faces wholesale stress—the UK PRA requires prior notification and caps concentration in upgrade swaps.
How are collateral swaps disclosed in Pillar 3 Asset Encumbrance templates?
Although securities borrowed via collateral swaps sit off balance sheet, both EBA Asset Encumbrance templates and Pillar 3 LIQ1 disclosures separately track encumbered on-balance-sheet assets pledged out alongside fair value of off-balance-sheet collateral received and re-usable, exposing synthetic HQLA reliance.
Publication record
- Published
- 14 November 2026
- Updated
- 17 November 2026
- Author
- Arthur Pendleton, CPA, JD
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Arthur Pendleton, CPA, JD. (2026, November 16). Collateral Swaps, Securities Lending & Liquidity Upgrade Trades: LCR30.36 Unwind & LCR40.48 Outflows. FinLexicon Wiki. https://finlexicon.org/wiki/collateral-swaps-securities-lending-lcr-upgrade-unwind-mechanicsRelated Liquidity Coverage Nsfr Prudential & Institutional Briefings
Explore Liquidity Coverage Nsfr Prudential Hub (20) →Liquidity Coverage Nsfr Prudential
Basel III LCR, NSFR, HQLA Haircuts & Intraday Prudential Liquidity ArchitectureLiquidity Coverage Nsfr Prudential
Contingent Funding Plans (CFP), Early Warning Indicators (EWIs) & Liquidity Funds Transfer Pricing (LFTP)Liquidity Coverage Nsfr Prudential
HQLA Level 1, 2A & 2B Haircuts: 40%/15% Composition Caps & Secured Funding Unwind (LCR30)Liquidity Coverage Nsfr Prudential
LCR 30-Day Deposit Run-Off Rates (LCR40): Stable Retail (3%/5%), Operational (25%) & Financial (100%)Liquidity Coverage Nsfr Prudential
LCR 75% Aggregate Cash Inflow Cap: Performing Loan Rollovers, SFTs & the 25% HQLA FloorLiquidity Coverage Nsfr Prudential
LCR Derivatives Collateral Outflows: 24-Month Historical Look-Back Approach (HLBA) & Rating TriggersLiquidity Coverage Nsfr Prudential
Undrawn Credit vs Liquidity Facilities in LCR40: Corporate (10%/30%), Bank (40%) & SPV (100%)Liquidity Coverage Nsfr Prudential
NSFR Available Stable Funding (ASF) Factors (NSF30): Tier 1/2 Capital, Retail & Sub-1Y CliffsIsda Csa Derivatives Collateral
2023 ISDA Digital Asset Derivatives Definitions: Fork Events, Oracle Disruptions & Basel SCO60 CapitalIfrs9 Cecl Credit Provisioning
IFRS 9 Stage 1, Stage 2 & Stage 3 ECL Migration: 12-Month vs Lifetime PD, Net Interest & Cure RulesIfrs9 Cecl Credit Provisioning
US GAAP ASC 326 (CECL): Day-One Lifetime Loss, R&S Reversion & ASU 2025-08 M&A Double-Count ReformIfrs9 Cecl Credit Provisioning
IFRS 9 vs CECL Procyclicality in Stress & Basel CET1 Regulatory Capital Transitional Phase-Ins
FinLexicon Wiki Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.