
Ifrs9 Cecl Credit Provisioning
Prudent Valuation Adjustment (PVA / AVA — EU CRR Art. 105 & Basel CAP50): 90% Confidence CET1 Deductions
Accounting Fair Value (IFRS 13 mid/exit) gives only a 50% expected value; under Basel CAP50 and EU/UK CRR Article 105, banks must deduct 90%-confidence Additional Valuation Adjustments (AVAs) directly from CET1.
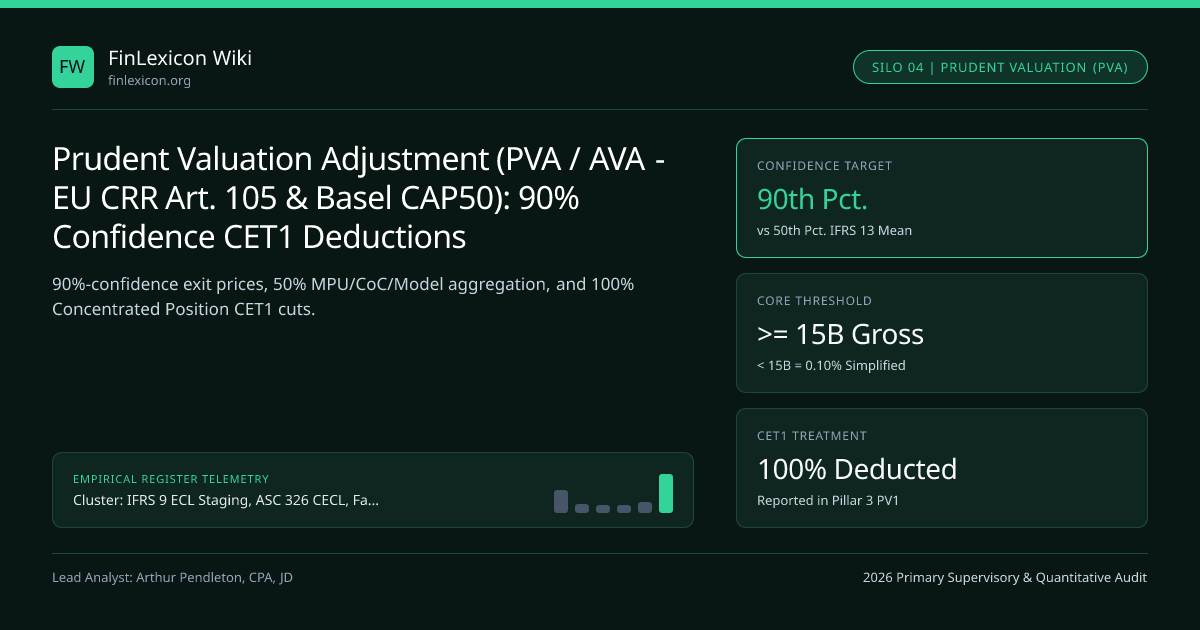
Accounting Fair Value under IFRS 13 and ASC 820 represents an unbiased 50th-percentile (mean / median) exit price—and explicitly forbids deducting P x Q blockage discounts on huge concentrated Level 1 equity stakes! Prudential bank regulators ask a far tougher solvency question: "If you actually had to exit or hedge that position promptly, what price could you achieve with 90% certainty?" Under Basel Framework chapter CAP50 and EU/UK CRR Articles 34 & 105 (EBA RTS 2016/101), the gap between Accounting Fair Value and 90%-Confidence Prudent Value—termed Additional Valuation Adjustments (AVAs)—is deducted 100% straight from Common Equity Tier 1 (CET1)!
Simplified Approach (0.1% Gross FV) vs Core Approach (90% Prudent Confidence)#
Applies across BOTH the Trading Book AND all Fair-Valued Banking Book (FVOCI / AFS / FVTPL) assets and liabilities (so sovereign FVOCI HQLA bonds suffer PVA deductions too!) at BNP Paribas, Berenberg Bank, and UK/EU subsidiaries supervised by the European Central Bank and UK PRA, anchored in our IFRS 9, CECL & Fair Value cornerstone guide:
- Simplified Approach (
Absolute Gross Fair ValueAssets + Liabilities < EUR 15 billion):Total_AVA = 0.10% (10 bps) * (|Fair_Value_Assets| + |Fair_Value_Liabilities|)(excluding exactly matched back-to-back trades). - Core Approach (
>= EUR 15 billion— Mandatory for All Major Banks): Computes nine distinct category-level AVAs calibrated to a 90th-percentile prudent exit confidence level!
The Nine Statutory EBA / PRA Additional Valuation Adjustment (AVA) Categories#
Under EBA Delegated Regulation (EU) 2016/101, Valuation Control Groups compute nine explicit AVAs (deducting any conservative fair-value reserves already booked in IFRS 13 accounting so nothing is double-counted!):
- Market Price Uncertainty (
MPUAVA): Dispersion across Totem/broker quotes at the 90th percentile (diversified across uncorrelated buckets via a50%aggregation factoralpha = 0.50!). - Close-Out Costs (
CoCAVA): Remaining 90th-percentile bid-offer spread uncertainty above IFRS 13 mid/portfolio bid-ask reserves (also benefits from the50%diversification factor!). - Model Risk AVA: Valuation range across plausible alternative mathematical models (e.g., Local Stochastic Vol vs Heston on autocallables—
50%diversification factor!). - Unearned Credit Spreads (
UCSAVA): Valuation uncertainty inside derivative CVA (captured inside MPU, CoC, and Model Risk). - Investing and Funding Costs (
IFCAVA): Uncertainty in FVA wholesale funding spreads. - Concentrated Positions AVA (
0%Diversification — Additive 100%!): Directly plugs IFRS 13’s blockage loophole! Whenever a position’s size exceeds 10-day normal market liquidity, banks must model a prudent multi-week exit price concession with ZERO diversification benefit (100%additive)! - Future Administrative Costs (
FACAVA):Ongoing operational/hedging servicing costs on books lacking executable lump-sum portfolio exit. - Early Termination AVA: Expected non-contractual client break concessions.
- Operational Risk AVA:
10%of (MPU + CoC) unless already covered under Pillar 1 SMA Operational Risk!
Transatlantic Divergence: Explicit EU/UK CRR Art. 105 PVA vs U.S. Supervisory Valuation Control#
Crucial jurisdictional contrast between BNP Paribas (EU CRR) and Bank of America (U.S. Reg Q): whereas EU CRR Art. 34/105 and UK PRA Rulebook publish a dedicated quarterly Pillar 3 PV1 Prudent Valuation template deducting EUR 1.0B–2.5B directly from G-SIB CET1 (-15 to -35 bps CET1!), the United States implements Basel CAP50 qualitatively via supervisory trading-book IPV exams and CCAR Global Market Shock haircuts rather than a formulaic PV1 line-item CET1 deduction!
Pillar 3 PV1 AVA Category | Target Valuation Uncertainty | Diversification Aggregation Factor (alpha) | Typical Share of Total G-SIB PVA |
|---|---|---|---|
1. Market Price Uncertainty (MPU) | 90% quote/Totem dispersion on mid prices | 50% (0.50 diversified) | ~28%–35% |
2. Close-Out Costs (CoC) | 90% executable bid-offer uncertainty | 50% (0.50 diversified) | ~20%–26% |
3. Model Risk (MR) | Dispersion across alternative pricing models | 50% (0.50 diversified) | ~15%–22% |
6. Concentrated Positions (CP) | >10-day market-depth exit concession | 0% (1.00 — Zero diversification!) | ~15%–25% |
| 4, 5, 7, 8, 9 (UCS, IFC, FAC, ET, Op) | CVA/FVA spread, servicing, break & op risk | 100% additive (UCS inside MPU/CoC/MR) | ~8%–14% |
Crisis Surge & the 2020 CRR Quick-Fix 66% Aggregation Adjustment#
During the March 2020 COVID bid-ask blowout, MPU and Close-Out Cost AVAs spiked procyclically across Eurozone banks—prompting the EBA temporarily to lift the diversification factor from 50% to 66% (34% weight instead of 50%) in 2020 before restoring the standard 50% calibration.
Avoiding Double-Counting Between Accounting Fair-Value Reserves (FVA/Bid-Ask) and CET1 AVA#
Increasing an accounting IFRS 13 Level 2/3 bid-ask or model reserve hits P&L (CET1), which reduces the incremental AVA deduction 1-for-1—keeping Total Prudent Capital (CET1_post_AVA) invariant across the IFRS 9, CECL & Fair Value Accounting topic hub!
- AVACategoryAgg = 0.50 * Sumi IndividualAVAi for Category in { MPU , CloseOutCost , Model_Risk }
- TotalPVADeduction = AVAMPU + AVACoC + AVAModel + 1.00 * ( AVAConcentrated + AVAIFC + AVAFAC + AVAET + AVAOp )
- Worked Concentrated Position Blockage Reconciliation (Bank Holds 12M Listed Shares @ EUR 50.00 Level 1 Screen Price = EUR 600.0M; ADV = 400k shares/day):
- 1. IFRS 13 Accounting Fair Value: Blockage discount STRICTLY FORBIDDEN -> Carrying Value = 12M * EUR 50.00 = EUR 600.00M.
- 2. EBA Art. 14 Concentrated Position Test: 12M shares = 30 days of 100% ADV (> 10-day prudent exit horizon -> Concentrated!).
- 3. 90%-Confidence Multi-Week Exit Price = EUR 46.50/sh (EUR 558.0M) => Concentrated AVA = EUR 600.0M - EUR 558.0M = EUR 42.0M (100% CET1 Deduction!)
Frequently asked questions
Why does PVA apply to FVOCI Banking Book government bonds, yet NOT to Amortized Cost (HTM) bonds?
Under CRR Article 105(1) and Basel CAP50.1, Prudent Valuation applies solely to positions measured at Fair Value because unrealized fair-value gains/marks flow directly into CET1 (once AOCI filters are removed); Amortized Cost / HTM positions are governed instead by credit ECL and IRRBB!
Why do Market Price Uncertainty and Close-Out Cost AVAs get multiplied by 50% (alpha = 0.50)?
If Desk 1 marks a bond vs 90% downside uncertainty and Desk 2 marks an uncorrelated FX option vs 90% downside uncertainty, summing two independent 90th-percentile tails 100% additively would produce a >99.5% portfolio-wide confidence level! Multiplying uncorrelated trade-level AVAs by 0.50 restores a portfolio-level 90% confidence level.
What are "Fall-Back Approach" 100% / 25% haircuts in EBA RTS 2016/101 when data is insufficient to model 90% confidence?
Whenever a bank lacks sufficient empirical data to compute a statistically credible 90%-confidence exit price on an exotic trade, EBA RTS Art. 7(2) Fall-Back imposes punitive flat haircuts: 100% of net unrealized profit plus 10% of notional (derivatives) or 25% of market value (cash securities)!
Does booking a more conservative accounting Fair-Value Reserve (e.g., wider IPV bid-ask reserve) penalize a bank’s CET1 twice?
No! Because Individual_AVA = Accounting_FV - Prudent_90pct_Exit_Value, booking an extra EUR 10M accounting bid-ask reserve reduces Accounting_FV (-EUR 10M P&L) and shrinks Individual_AVA (-EUR 5M to -EUR 10M), avoiding double counting.
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Arthur Pendleton, CPA, JD
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Arthur Pendleton, CPA, JD. (2026, November 14). Prudent Valuation Adjustment (PVA / AVA — EU CRR Art. 105 & Basel CAP50): 90% Confidence CET1 Deductions. FinLexicon Wiki. https://finlexicon.org/wiki/prudent-valuation-adjustment-pva-ava-cet1-core-market-priceRelated Ifrs9 Cecl Credit Provisioning & Institutional Briefings
Explore Ifrs9 Cecl Credit Provisioning Hub (20) →Ifrs9 Cecl Credit Provisioning
IFRS 9 Expected Credit Loss, US GAAP ASC 326 CECL, Fair Value Hierarchy & Hedge Accounting GuideIfrs9 Cecl Credit Provisioning
xVA Valuation Adjustments (CVA, DVA, FVA, KVA & MVA): IFRS 13 / ASC 820 Accounting vs Basel MAR50 CapitalIfrs9 Cecl Credit Provisioning
Own-Credit Risk on Fair-Value Option Liabilities (IFRS 9.5.7.7 & ASC 825-10): OCI & Basel CET1 FiltersIfrs9 Cecl Credit Provisioning
IFRS 9 General Hedge Accounting vs US GAAP ASC 815: Rebalancing, Cost of Hedging OCI & Effectiveness RulesIfrs9 Cecl Credit Provisioning
Portfolio Macro Fair-Value Hedge Accounting: EU IAS 39 Carve-Out, US GAAP Portfolio Layer Method & IASB DRMIfrs9 Cecl Credit Provisioning
Off-Balance-Sheet Loan Commitments & Guarantees: IFRS 9 Behavioral CCF vs ASC 326 Cancellable RulesIfrs9 Cecl Credit Provisioning
Loan Modifications, Forbearance & 10% Derecognition Test (IFRS 9.5.4.3 vs US GAAP ASU 2022-02 TDR Repeal)Ifrs9 Cecl Credit Provisioning
Day-1 P&L Deferral (IFRS 9.B5.1.2A vs US GAAP ASC 820): Level 3 Calibration Reserves & Release RulesCentral Clearing Ccp Waterfall
SEC Exchange Act Rule 15c3-3a Note H: Broker-Dealer Customer U.S. Treasury Margin On-Posting to FICCCentral Clearing Ccp Waterfall
FICC Capped Contingency Liquidity Facility (CCLF): Cover-1 Repo Liquidity Sizing & Bank LCR ImpactCentral Clearing Ccp Waterfall
CCP Margin Anti-Procyclicality (APC): EMIR RTS Article 28 25% Buffer, 10-Year Stress Weight & Margin FloorsCentral Clearing Ccp Waterfall
CCP Default Management Groups (DMG), Macro Hedging, Auction Juniorization & 2018 Nasdaq Lessons
FinLexicon Wiki Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.